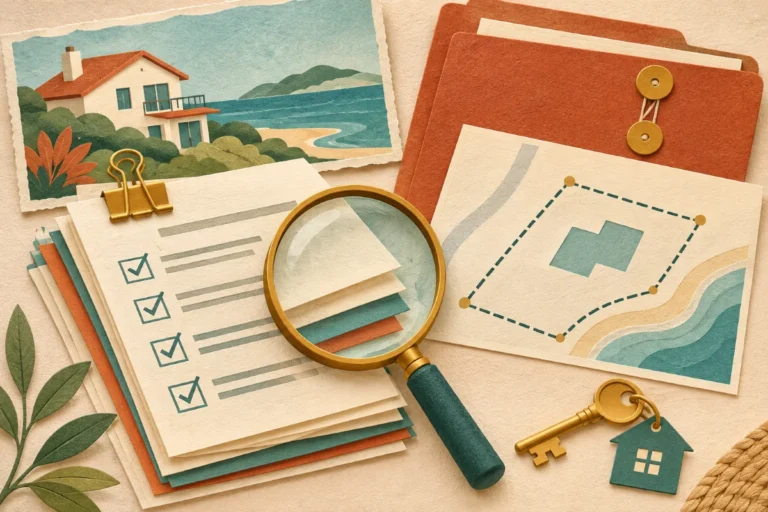
Build a due-diligence file before evaluating a fractional proposal
Organize identities, property evidence, governing documents and unresolved questions into a reviewable file.
 FractionalOwnershipAruba.comIndependent ownership research · A division of Aruba Web Services
 ABCIslandsFerry.com
 ArubaActivityDeals.com
 ArubaAds.com
 ArubaBars.com
 ArubaBeaches.ca
 ArubaBeachHouse.ca
 ArubaBeachHouse.com
 ArubaCarsForSale.com
 ArubaCasinos.ca
 ArubaPortCity.com
 ArubaDentist.com
 ArubaDirectory.com
 ArubaFastFood.com
 ArubaFoodTrucks.com
 ArubaFurnitureStores.com
 ArubaGolfing.com
 ArubaGroceries.com
 ArubaHappyHour.ca
 ArubaHappyHours.ca
 ArubaMarinePark.ca
 ArubaNews.caArubaPortCity.com
 ArubaRecycling.com
 ArubaTimesharesForSale.com
 ArubaTransportation.com
 ArubaVacationCondo.com
 ArubaWebcams.ca
 ArubaWebServices.com
 DiscoverAruba.ca
 DowntownOranjestad.com
 DronePilotsAruba.com
 FractionalOwnershipAruba.com
 InvestInAruba.ca
 JoomlaAruba.com
 LotusJewelsAruba.com
 OwnInAruba.com
 PortCityAruba.com
 RentACondoInAruba.com
 RentAHomeInAruba.com
 RentAVillaInAruba.com
 SanNicolasFerry.com
 ScubaInAruba.ca
 SoldOnAruba.com
 SunsetCondosAruba.com
 VisitAruba.ca
 WacamayaCondosAruba.com
 WacamayaOwners.com
Organize identities, property evidence, governing documents and unresolved questions into a reviewable file.
Investigate transfer restrictions, valuation, continuing duties and dispute routes before committing.
Separate legal, tax, identity and operational questions and bring an organized evidence file.
Look past the label and map the interest, the underlying asset and the documents that connect them.
Compare allocation, cancellations and unavailable periods before treating a fraction as a holiday entitlement.
Separate acquisition, recurring charges, reserves and exit costs without inventing returns or Aruba tax rates.